

GO2bank: Mobile banking

- 15.96K Reviews
- 4.4
- Downloads
- 5,000,000+
Our take on GO2bank: Mobile banking from Appgk
I approached GO2bank as a practical money-management tool rather than just another banking download. It is a free finance app from Green Dot, aimed at people who want to handle everyday banking from a phone. After spending time with its layout and workflow, my impression is that it makes routine tasks feel approachable, while still asking users to pay close attention to account terms and the limits of a mobile-first service.
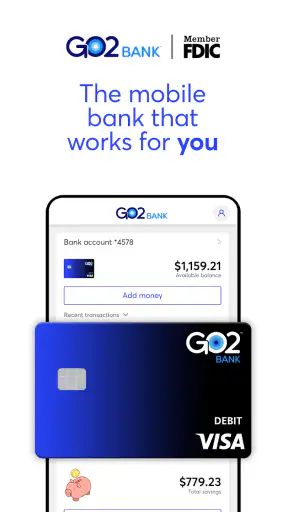
The app’s store summary calls it “the mobile bank that works for you,” but that promise is most convincing when your needs are straightforward: checking your balance, keeping an eye on spending, and managing money without relying on a traditional branch. It is available for everyone from a content-rating perspective, runs on Android starting with version 9, and currently sits at version 3.2.0. Those details matter because this is not positioned as a specialist investment platform or a budgeting game; it is a day-to-day banking companion.
How GO2bank feels in its current form
The first thing I noticed is that the experience is built around quick access. A mobile banking app succeeds when I can open it, understand my available money, and finish a basic task without wandering through unrelated screens. GO2bank generally follows that principle. The presentation is less intimidating than many full-service financial apps, which can be useful if you are opening your first account or simply prefer a clean, focused interface.
That simplicity also reveals the app’s intended audience. I would recommend it to someone who wants a phone-based place for everyday banking and values convenience over a large collection of financial products. It can also suit users who are tired of managing several separate tools for checking balances and monitoring transactions. On the other hand, someone looking for detailed investment analysis, sophisticated household budgeting, or a broad wealth-management dashboard will probably find the experience too narrow.
Best Parts of GO2bank: Mobile banking
Things to Keep in Mind About GO2bank: Mobile banking
GO2bank has built a sizable audience, with more than five million installs, and its average rating is 4.4 from roughly one hundred five thousand ratings. I see that as evidence that the basic proposition works for many people, not proof that every user will have a smooth experience. Banking apps are especially personal: a feature that feels wonderfully simple to one person can feel restrictive to another, particularly when money needs are more complicated than everyday spending.
Where the app is genuinely useful
My favorite use case is the “quick check” habit. Before buying groceries, paying for a ride, or sending money toward a bill, I can use a mobile bank to confirm what is available rather than relying on memory. That small step helps prevent accidental overspending. GO2bank is well suited to this kind of repeated interaction because its value comes from being available during ordinary moments, not from asking me to perform a long financial review every evening.
News and Features Related to GO2bank: Mobile banking

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
News
Moovit Review: A More Reliable Way to Navigate Everyday Transit
News
Mastering Screen Recorder - XRecorder: Pro Tips for Mobile Video
It is also useful for separating purposes. A user might treat the account as a dedicated place for regular expenses while keeping another account for savings or long-term commitments. I would not call that a universal recommendation, but it can make spending easier to understand. The important discipline is to decide in advance what the account is for and then check activity consistently. A second account only helps when it reduces confusion rather than creating another balance to remember.
One practical tip is to use the app as a checkpoint before recurring obligations are due. Rather than checking only after a payment has gone through, I would look at the account beforehand and leave enough room for expected withdrawals. This is not a magical budgeting feature; it is a workflow advantage. The phone makes the check convenient, but the user still has to build the habit and understand which transactions are pending, completed, or still expected.
Don't want to read the full review?
What has changed and what that means
The app was released on November 10, 2020, and its current version is 3.2.0. That combination suggests an established product that has moved beyond its initial launch rather than a brand-new experiment. I would read the version history as a sign of ongoing maintenance and refinement, but not as a reason to assume that every requested banking feature has been added. A version number alone cannot tell me whether a particular workflow is ideal for my needs.
For existing users, the most important effect of continued development is usually stability and familiarity. People do not want a banking app to reinvent its navigation every few months. A mature interface can make routine checks faster because muscle memory develops around the same core actions. At the same time, updates can change where controls appear or how information is presented, so I would still review the app after an update instead of tapping through automatically.
Screenshots
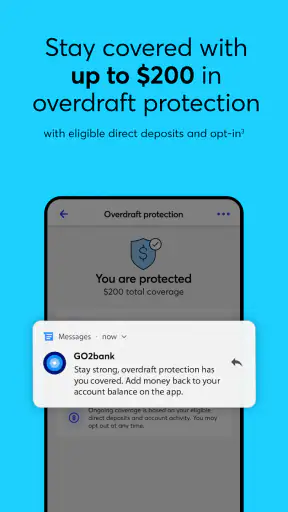
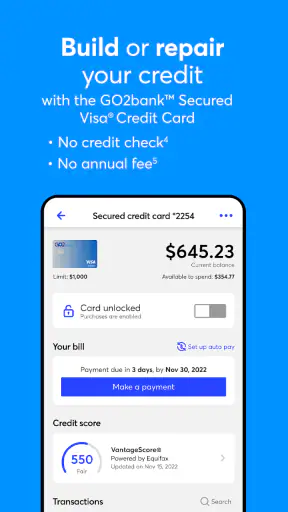
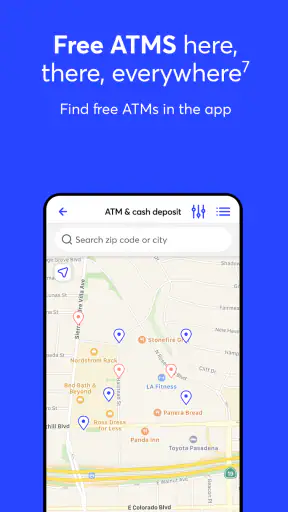
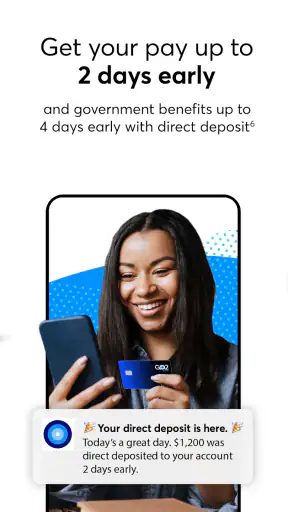
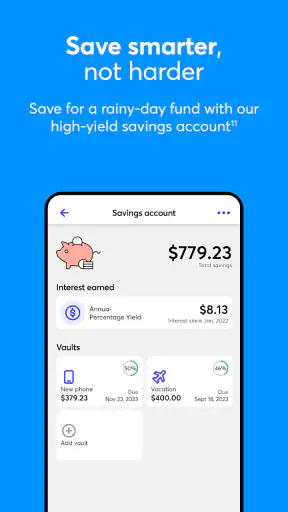
There is a useful distinction here between product evolution and product expansion. A banking app may become easier to use without becoming a complete replacement for every financial service. In my view, GO2bank’s current direction is most compelling when it improves access to ordinary banking rather than trying to imitate a brokerage, a tax tool, and a detailed budgeting suite all at once. That focus can be a strength if your expectations match it.
New users should also remember that a polished mobile interface does not remove the need to read account information carefully. Before moving regular income or important bill money into any mobile banking service, I would examine the applicable account terms, transaction conditions, and support process. The app can make access convenient, but convenience should not be confused with unlimited flexibility.
Everyday workflow: using it without losing control
Imagine I am paid, need to cover household expenses, and want to avoid spending money reserved for bills. I would begin by checking the available balance, then review recent activity to make sure the account reflects what I expect. Next, I would leave a deliberate cushion instead of treating the displayed amount as permission to spend everything. Later in the week, I would check again after purchases settle. This simple routine is where GO2bank can earn its place on my phone.
The non-obvious lesson is that a mobile bank works best when paired with a personal rule. For example, I might decide that the account is checked before any unusually large purchase, not just at the start of the month. That turns the app from a passive statement viewer into a decision point. It also reduces the risk of assuming that a familiar balance means all upcoming commitments have already been accounted for.
Another useful approach is to keep a short external note of expected obligations. I would not depend on the app alone to remember every future payment unless the relevant information is clearly available in my account view. A simple list of rent, utilities, subscriptions, and planned transfers gives context that a transaction feed may not provide. This is a trade-off: GO2bank offers quick access to banking information, while a separate planning method may still be better for seeing the whole month.
For shared household finances, I would be more cautious. If several people need detailed visibility, approval steps, or coordinated planning, a conventional joint-banking setup or a dedicated household budgeting service may fit better. GO2bank can be convenient for an individual’s daily use, but convenience for one person does not automatically solve the communication problems of a family or group.
Security, access, and the points that deserve attention
Because this is a finance app, I judge it differently from a social or entertainment app. I would install it only on a device I keep updated and protected, use a strong unique sign-in method, and avoid checking sensitive account information on an unfamiliar network. These are not special GO2bank features; they are sensible habits whenever an app gives access to money.
I would also prepare for the possibility that mobile access is temporarily inconvenient. A phone can be lost, damaged, out of battery, or unavailable at the exact moment I need to confirm a balance. For that reason, I would not make the app my only source of financial organization. Keeping essential payment details and a basic emergency plan elsewhere is a small precaution that becomes valuable when technology is not cooperating.
Support expectations matter too. In a branch-based relationship, I may be able to walk in and explain a problem face to face. With a mobile-first bank, I need to be comfortable resolving questions through digital support channels and account guidance. That does not make the app a poor choice, but it is a meaningful difference from traditional alternatives. If personal assistance is central to how you manage money, I would compare that experience before switching.
Where GO2bank still has limits
The biggest limitation is not necessarily a missing button; it is the narrowness of the mobile-banking model. If I want advanced spending categorization, long-range financial projections, investment research, or highly customized reporting, I would probably combine GO2bank with another tool or choose a broader financial platform. The app’s strength is direct access, not an all-in-one financial command center.
I would also avoid treating the free price as the whole cost question. A free download is attractive, but banking decisions should be based on the account’s terms and the situations in which charges or restrictions may apply. I would read those details before arranging deposits or recurring payments. This is especially important for users who maintain a tight balance, because a small unexpected condition can matter more than a polished interface.
Users who travel frequently, manage multiple currencies, or need specialized international banking should compare alternatives carefully. A straightforward domestic routine and a complex cross-border lifestyle place very different demands on an account. GO2bank may be a sensible everyday option for one person and an awkward primary account for another. My advice is to test the fit against your actual money movements, not against the app’s general appearance.
There is also a psychological limitation. Fast balance access can encourage frequent checking, which is helpful when it supports awareness but stressful when it becomes constant reassurance-seeking. I prefer setting a few deliberate check-in points: before major spending, around expected income, and after important payments. That gives the app a clear role without allowing every notification or balance change to dominate my attention.
How it compares with familiar alternatives
Compared with a traditional bank’s app, GO2bank feels more focused on the mobile relationship itself. A conventional bank may offer a wider branch network, more account types, or a longer-established service structure, while GO2bank appeals to someone who wants to do routine banking from a phone. The better choice depends on whether physical access and a broad product range matter more to you than a direct, mobile-centered experience.
Compared with prepaid or wallet-style tools, a mobile bank can feel more suitable for users who want an account they treat as part of their regular financial routine. However, I would still compare how each option handles deposits, transfers, spending, support, and account conditions. The label on the app is less important than the exact workflow you need every week.
Compared with budgeting apps, GO2bank serves a different purpose. A budgeting app may give me a wider view across several accounts and help me plan categories, but it is not necessarily the place where I conduct everyday banking. GO2bank can provide the account access, while a separate planner supplies broader context. That combination may be more useful than expecting one app to do both jobs perfectly.
My practical comparison test is simple: list the three actions I perform most often and the two problems I most need to avoid. If those actions are basic account checks and routine money management, GO2bank deserves consideration. If the problems involve complex forecasting, investment decisions, or extensive shared finances, another service may be the better foundation.
Who should try it and who should skip it
I think GO2bank is a good fit for adults who want a free mobile finance app for ordinary banking and who are comfortable taking responsibility for monitoring their own account. It may be particularly appealing to someone who prefers a phone over a branch and wants a less cluttered starting point than a large financial super-app.
I would be less enthusiastic for a user who needs face-to-face service, highly detailed planning tools, complex business banking, or a single platform for investments and long-term financial analysis. I would also hesitate if the person rarely has reliable phone access or dislikes resolving account questions digitally. Those are not minor preferences; they shape whether the service will feel dependable in real life.
Families should decide separately whether the app fits their coordination needs. An individual can keep a clear personal routine, but shared expenses often require permissions, communication, and visibility beyond a simple mobile account check. In that situation, I would compare GO2bank with a joint account arrangement and a dedicated budgeting system before making it the household’s main option.
What I would watch as the app continues to evolve
As the product develops, I would pay attention to whether updates make common tasks clearer without adding unnecessary complexity. The best improvement would be one that helps users understand available money, recent activity, and upcoming obligations at a glance. I would also watch how clearly changes to account conditions and support processes are communicated, because transparency matters just as much as visual polish in a finance app.
I would not judge future progress solely by a higher version number. I would look for smoother recovery when something goes wrong, clearer explanations around transactions, and a dependable path to help. Those details are easy to overlook during a first download but become decisive when money is delayed, misread, or urgently needed.
After using GO2bank, my conclusion is measured but positive. It is not the right answer to every banking problem, and I would not choose it as a substitute for specialized financial planning. Still, for a person who wants a focused mobile account and is willing to stay attentive to terms and balances, it can be a practical everyday companion. The strongest reason to choose it is simple access paired with disciplined personal habits.
Green Dot’s app is free, rated for Everyone, and supported by a substantial user base, but those facts should be the beginning of your decision rather than the end. I would install it when my priority was convenient routine banking from a phone. I would skip it when I needed branch-based help, advanced analysis, or a more expansive financial toolkit. Used within its natural role, GO2bank feels useful; expected to solve every money-management need, it becomes a less convincing choice.
GO2bank: Mobile banking FAQ
What is GO2bank, and who can use the app?
GO2bank is a mobile banking app designed for managing everyday finances from an Android or iOS device. After opening an account, users can generally check balances, receive direct deposits, pay bills, transfer money, deposit checks, and use a GO2bank debit card. Availability, eligibility, identity-verification requirements, and certain features may depend on your location and account status.
Is GO2bank free to use, or are there fees?
GO2bank offers several useful banking services, but it is not completely fee-free in every situation. Depending on how you use the account, charges may apply for monthly service, out-of-network ATM withdrawals, cash deposits, expedited services, or other transactions. Before downloading or relying on the app, review the current fee schedule and look for qualifying conditions that may waive particular fees.
Can I deposit money and receive my paycheck through GO2bank?
Yes, GO2bank is built to support common deposit options, including direct deposit for paychecks or eligible government benefits. The app may also provide mobile check deposit and ways to add cash at participating retailers, although availability, limits, processing times, and possible fees can vary. Always confirm deposit instructions and timing inside the current version of the app.
How secure is the GO2bank mobile banking app?
GO2bank uses standard mobile-banking protections such as account authentication, encrypted connections, transaction monitoring, and security alerts, while supported devices may also allow fingerprint or face-based sign-in. Security still depends on your habits: install the app only from an official store, keep your phone updated, avoid sharing verification codes, use a unique password, and contact support immediately if you notice suspicious activity.
What can I do if I have trouble logging in or my card is lost?
If you cannot sign in, use the app’s password or account-recovery options and make sure your phone number, email address, and app version are current. For a lost or stolen GO2bank card, lock or replace it as quickly as possible through the app or official customer-support channels. Never use contact details from unofficial websites or messages, and monitor recent transactions for unauthorized activity.













